Making Tax Digital Income Tax
6 min read
Want a simple overview first?
Download the free guide for UK sole traders and understand the key accounting records, deadlines and Making Tax Digital changes in plain English.
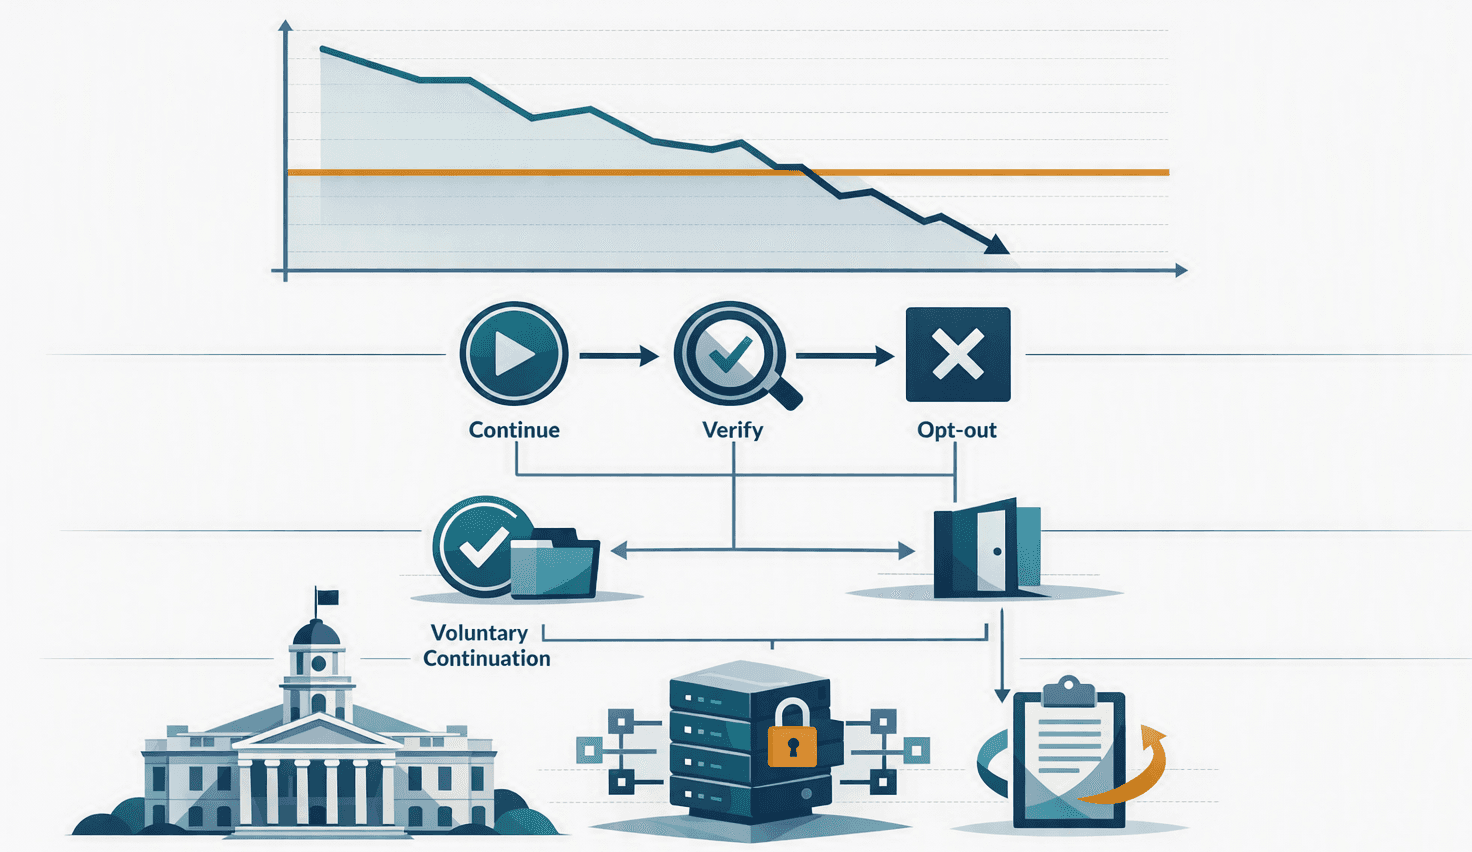
The threshold is based on qualifying income
Qualifying income is broadly your gross self-employment and property income before expenses. MTD is being phased in using thresholds of over £50,000, over £30,000 and then over £20,000.
One lower year may not be enough
The rules for leaving MTD depend on your circumstances and HMRC's records. Do not simply stop creating digital records or sending updates because turnover has fallen.
Opting out is an action
Where you are eligible to leave MTD, follow HMRC's formal process through your online services. If your income source ceases, separate cessation rules can apply.
You may also stay voluntarily
In some circumstances you can continue using MTD voluntarily even if you are no longer required to do so.
Common misconception
“If my income drops below the threshold this year, I can simply stop sending MTD updates.”
Not true.
Check the formal HMRC rules and your account first.
Do not stop MTD just because turnover falls. Confirm whether you are eligible to leave and follow the HMRC process.

READY FOR THE NEXT STEP?
Explore my practical guides for UK sole traders, covering accounting essentials and Making Tax Digital software in plain English.

KEEP READING
Related Articles

MAKING TAX DIGITAL
Do I Need to Use Making Tax Digital?
Find out whether Making Tax Digital applies to your business, when the new rules start, and what you need to do to stay compliant.
Read Article

MAKING TAX DIGITAL
What Actually Changes Under Making Tax Digital?
Discover the biggest changes introduced by Making Tax Digital, from digital record keeping to quarterly updates and year-end submissions.
Read Article
MAKING TAX DIGITAL
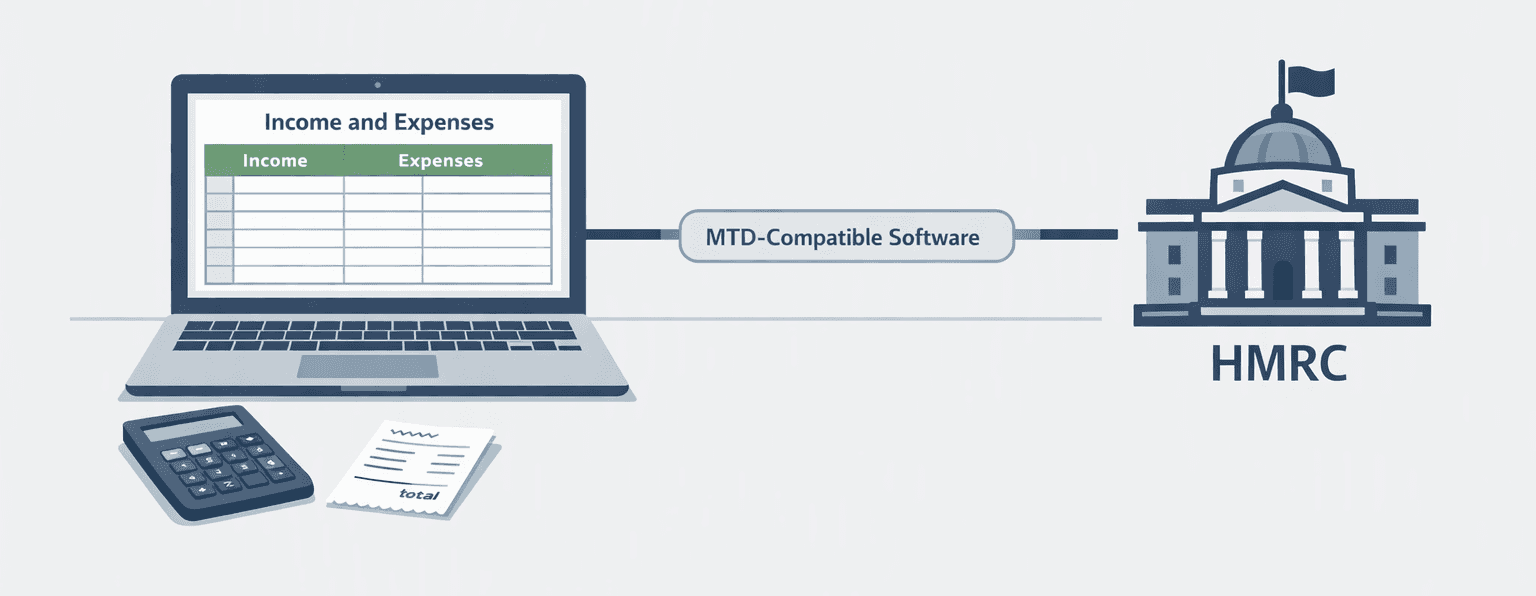
Can I Still Use Excel for Making Tax Digital?
A plain-English look at spreadsheets, software and what compatible digital records mean.
Read Article